A severe storm can leave Toronto and GTA homeowners with a difficult question: is my roof damaged, and if so, what do I do about it?
This guide walks through the roof insurance claim process in Ontario in plain language. It is general education only — not legal advice, and not an interpretation of your specific insurance policy. Coverage and claim decisions depend on your individual policy, the cause of loss, exclusions, your deductible, and your insurer. The insurance company determines coverage and settlement.
Important: Eagle Roofing is an independent roofing contractor. We inspect and document observable roofing conditions and provide roofing estimates and documentation. We do not determine insurance coverage or claim settlements, and we cannot guarantee that any claim will be approved.
1. What Homeowners Should Do Immediately After a Storm
Safety comes first. After a storm, do not climb onto a wet, icy, steep, or damaged roof. From the ground, and only when it is safe to do so, take photographs of any visible damage, fallen materials, water intrusion, or other relevant conditions. Then review your insurance policy and contact your insurer to understand your coverage, deductible, and reporting requirements.
- Stay safe — don't climb onto a wet, icy, steep, or damaged roof.
- Document what you can safely observe with photographs from the ground.
- Review your insurance policy and contact your insurer to understand your coverage and claim requirements.
- Have the roof professionally assessed to document observable conditions.
- Keep all photographs, estimates, invoices, and communications in one place.
2. Common Types of Observable Wind and Storm Roof Damage
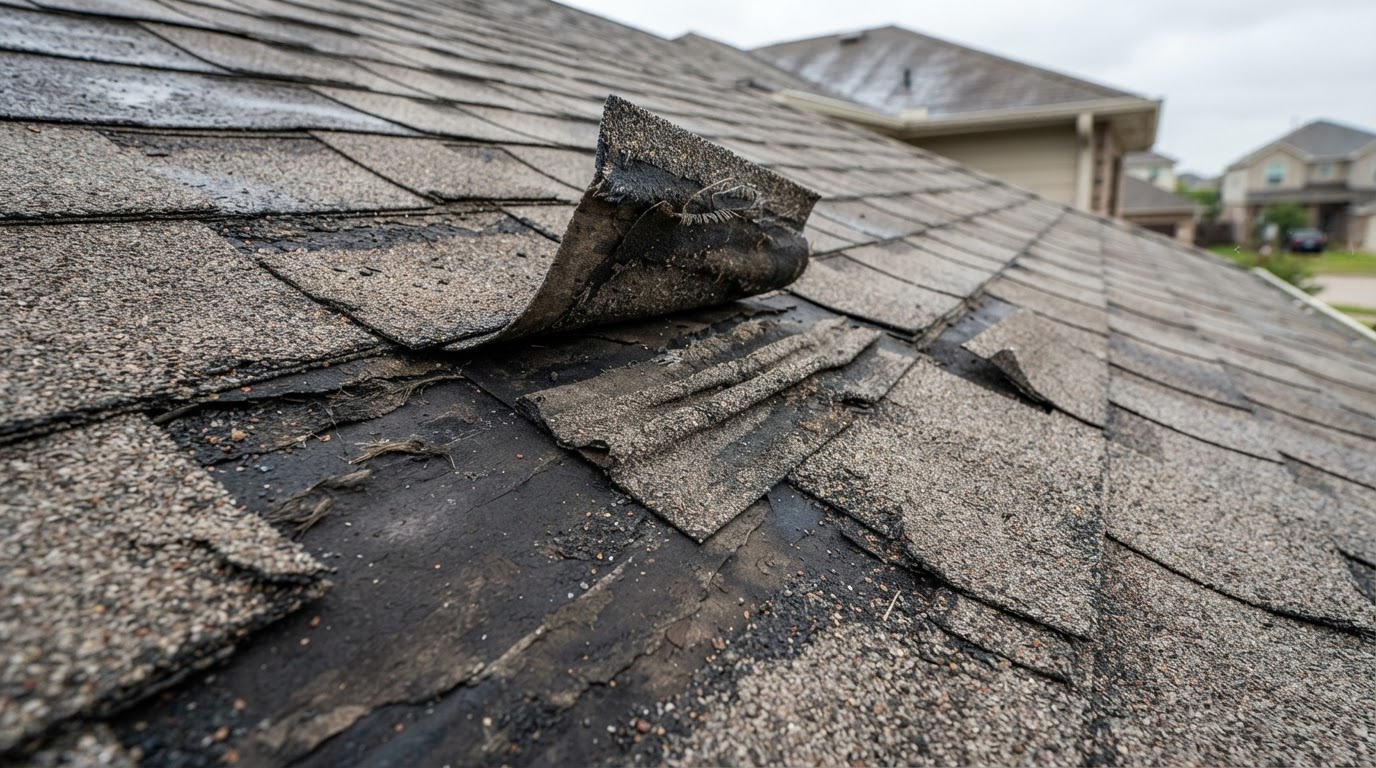
Storm damage isn't always obvious from the ground. Common observable conditions include:
- Missing or lifted shingles
- Creased or folded shingle tabs
- Wind-damaged or displaced roof coverings
- Damaged flashing around chimneys, valleys, and transitions
- Damage around vents, skylights, and penetrations
- Water intrusion or active leaks
- Debris impact, dents, or punctures
The presence of these conditions does not automatically mean insurance coverage applies. Your insurer will consider the cause of loss, your policy terms, and any exclusions.
3. How Homeowners Typically Start an Insurance Claim
Most insurers allow you to start a claim online, by phone, or through your broker. You'll typically be asked to describe what happened, when, and what damage you've observed. Your insurer will explain the next steps, which may include an adjuster visit or a request for estimates and documentation.
Before filing, it's worth reviewing your policy and deductible and speaking with your insurer about coverage and claim requirements. We do not advise that you should always file a claim — the right decision depends on your circumstances.
4. The Role of the Insurance Company and Adjuster
Your insurance company determines whether a loss is covered and what amount, if any, is payable under your policy. They may assign an adjuster to inspect the damage, review your documentation, and assess the claim. The adjuster works on behalf of the insurer to evaluate the loss according to your policy terms, conditions, exclusions, and deductible.
5. The Role of a Professional Roofing Contractor
A roofing contractor's role is on the roofing side of the process. Eagle Roofing inspects observable roofing conditions, documents findings, and provides roofing estimates and scope information. We do not determine insurance coverage or claim settlements.
6. What Eagle Roofing Can Inspect and Document
We can provide this documentation to you or, where appropriate, to the adjuster — and communicate regarding the roofing scope when appropriate.
7. Repair Versus Replacement — and Who Makes the Coverage Decision
Not every storm-damaged roof requires replacement. Damage may be isolated and repairable, or it may be widespread. A professional inspection documents the observable conditions, and repair or replacement is recommended based on the actual roofing conditions and the work required.
However, your insurance company determines what is covered under your policy. Eagle Roofing cannot guarantee that a repair or replacement will be covered, or that an insurer will pay for it.
8. Deductibles and Policy Limitations
Most policies include a deductible — the amount you pay out of pocket before insurance contributes. Policies may also include exclusions, coverage limits, and conditions that affect what is payable. Review your policy and speak with your insurer to understand how your deductible and any limitations apply to your situation.
9. Why Photographs and Documentation Matter
Documentation helps establish the condition and history of your roofing system. Dated photographs, inspection reports, maintenance records, repair invoices, and contractor estimates all contribute to a clear, factual record.
Documentation Supports — But Doesn't Guarantee
Good documentation can support your claim with factual information, but it does not guarantee insurance coverage or claim approval. Coverage and settlement decisions are made by your insurance provider based on your policy and the circumstances of the loss.
10. What Happens After a Claim Is Approved
If your insurer approves a claim, they will explain the settlement and any conditions. Eagle Roofing can then provide repair or replacement proposals based on the actual roofing conditions and the work required, and complete the authorized roofing work to a professional standard.
11. What Happens if Additional Roofing Conditions Are Discovered
Sometimes, during repairs or replacement, additional roofing conditions are discovered that weren't visible during the initial inspection. If this happens, Eagle Roofing documents the new findings and can provide updated scope information. You would then discuss any additional coverage with your insurer — coverage decisions remain with the insurance company.
12. Frequently Asked Questions
Does homeowners insurance cover roof storm damage?
It depends on your individual policy, the cause of loss, your deductible, and any exclusions. Many policies cover sudden and accidental wind or hail damage, but coverage varies. Your insurer determines coverage. Eagle Roofing cannot determine your coverage.
Should I call my insurance company or a roofer first?
Both can be helpful. Contact your insurer to understand your policy and claim requirements. A professional roofing assessment establishes what observable damage exists and what roofing work may be required — but Eagle Roofing cannot determine whether your policy will cover that work.
Does wind damage mean my entire roof will be replaced?
Not necessarily. Damage may be isolated and repairable, or widespread. A professional inspection documents the observable conditions, and repair or replacement is recommended based on the actual conditions. Your insurer determines what is covered.
Can Eagle Roofing meet or communicate with an insurance adjuster?
Where appropriate, Eagle Roofing can provide roofing documentation and communicate regarding the roofing scope. Eagle Roofing does not determine insurance coverage or claim settlements — those decisions are made by your insurance provider.
What documentation can Eagle Roofing provide?
We can provide dated photographs, a written inspection report, roof measurements where required, repair or replacement estimates, and scope and material information that may be useful during your insurance claim process.
Who determines whether my roof repair or replacement is covered?
Your insurance company determines coverage and settlement based on your policy, the cause of loss, exclusions, and your deductible. Eagle Roofing is an independent roofing contractor and does not make coverage decisions.
Will a roof inspection guarantee my insurance claim is approved?
No. A professional inspection documents observable roofing conditions and can support your claim with factual information, but it does not guarantee approval. Coverage decisions are made by your insurance provider.
Can Eagle Roofing complete emergency repairs?
Yes, where appropriate and safely possible, Eagle Roofing can perform emergency or weatherproofing work to help prevent further damage. Permanent repairs or replacement are completed following authorization.
13. When to Contact Eagle Roofing
If your roof may have been damaged by wind, hail, or a recent storm, the sooner it's professionally assessed, the better. Eagle Roofing can inspect and document observable roofing conditions, provide clear recommendations, and supply the roofing documentation that may be useful during your insurance claim process.
You may also find it helpful to read about our roof repair and roof replacement services, or our Pre-Winter Roof Health Assessment.
Concerned Your Roof Was Damaged by a Storm?
Eagle Roofing can professionally assess and document observable roofing conditions and provide clear recommendations for any roofing work that may be required.
Eagle Roofing — Excellence Above Everything.
Disclaimer: This article is provided for general educational purposes only and does not constitute legal advice or an interpretation of any specific insurance policy. Eagle Roofing is an independent roofing contractor and does not determine insurance coverage or claim settlements. Coverage and payment decisions are made by the homeowner's insurance provider and are subject to the terms, conditions, exclusions, and deductible of the applicable policy.